Get every episode summarized
Each time Sourcery publishes, we email you a written briefing from the transcript — the topics, who appeared, and any specific claims, with the ad reads skipped.
Email me new episodesFree for 3 shows. No card needed.
About this episode
Sourcery is made possible by:
“We have half a billion monthly active users. We have built over the past decade in operating system of over 50 proprietary technologists. We buy these companies and then we install them on this shared operating system.”From the transcript
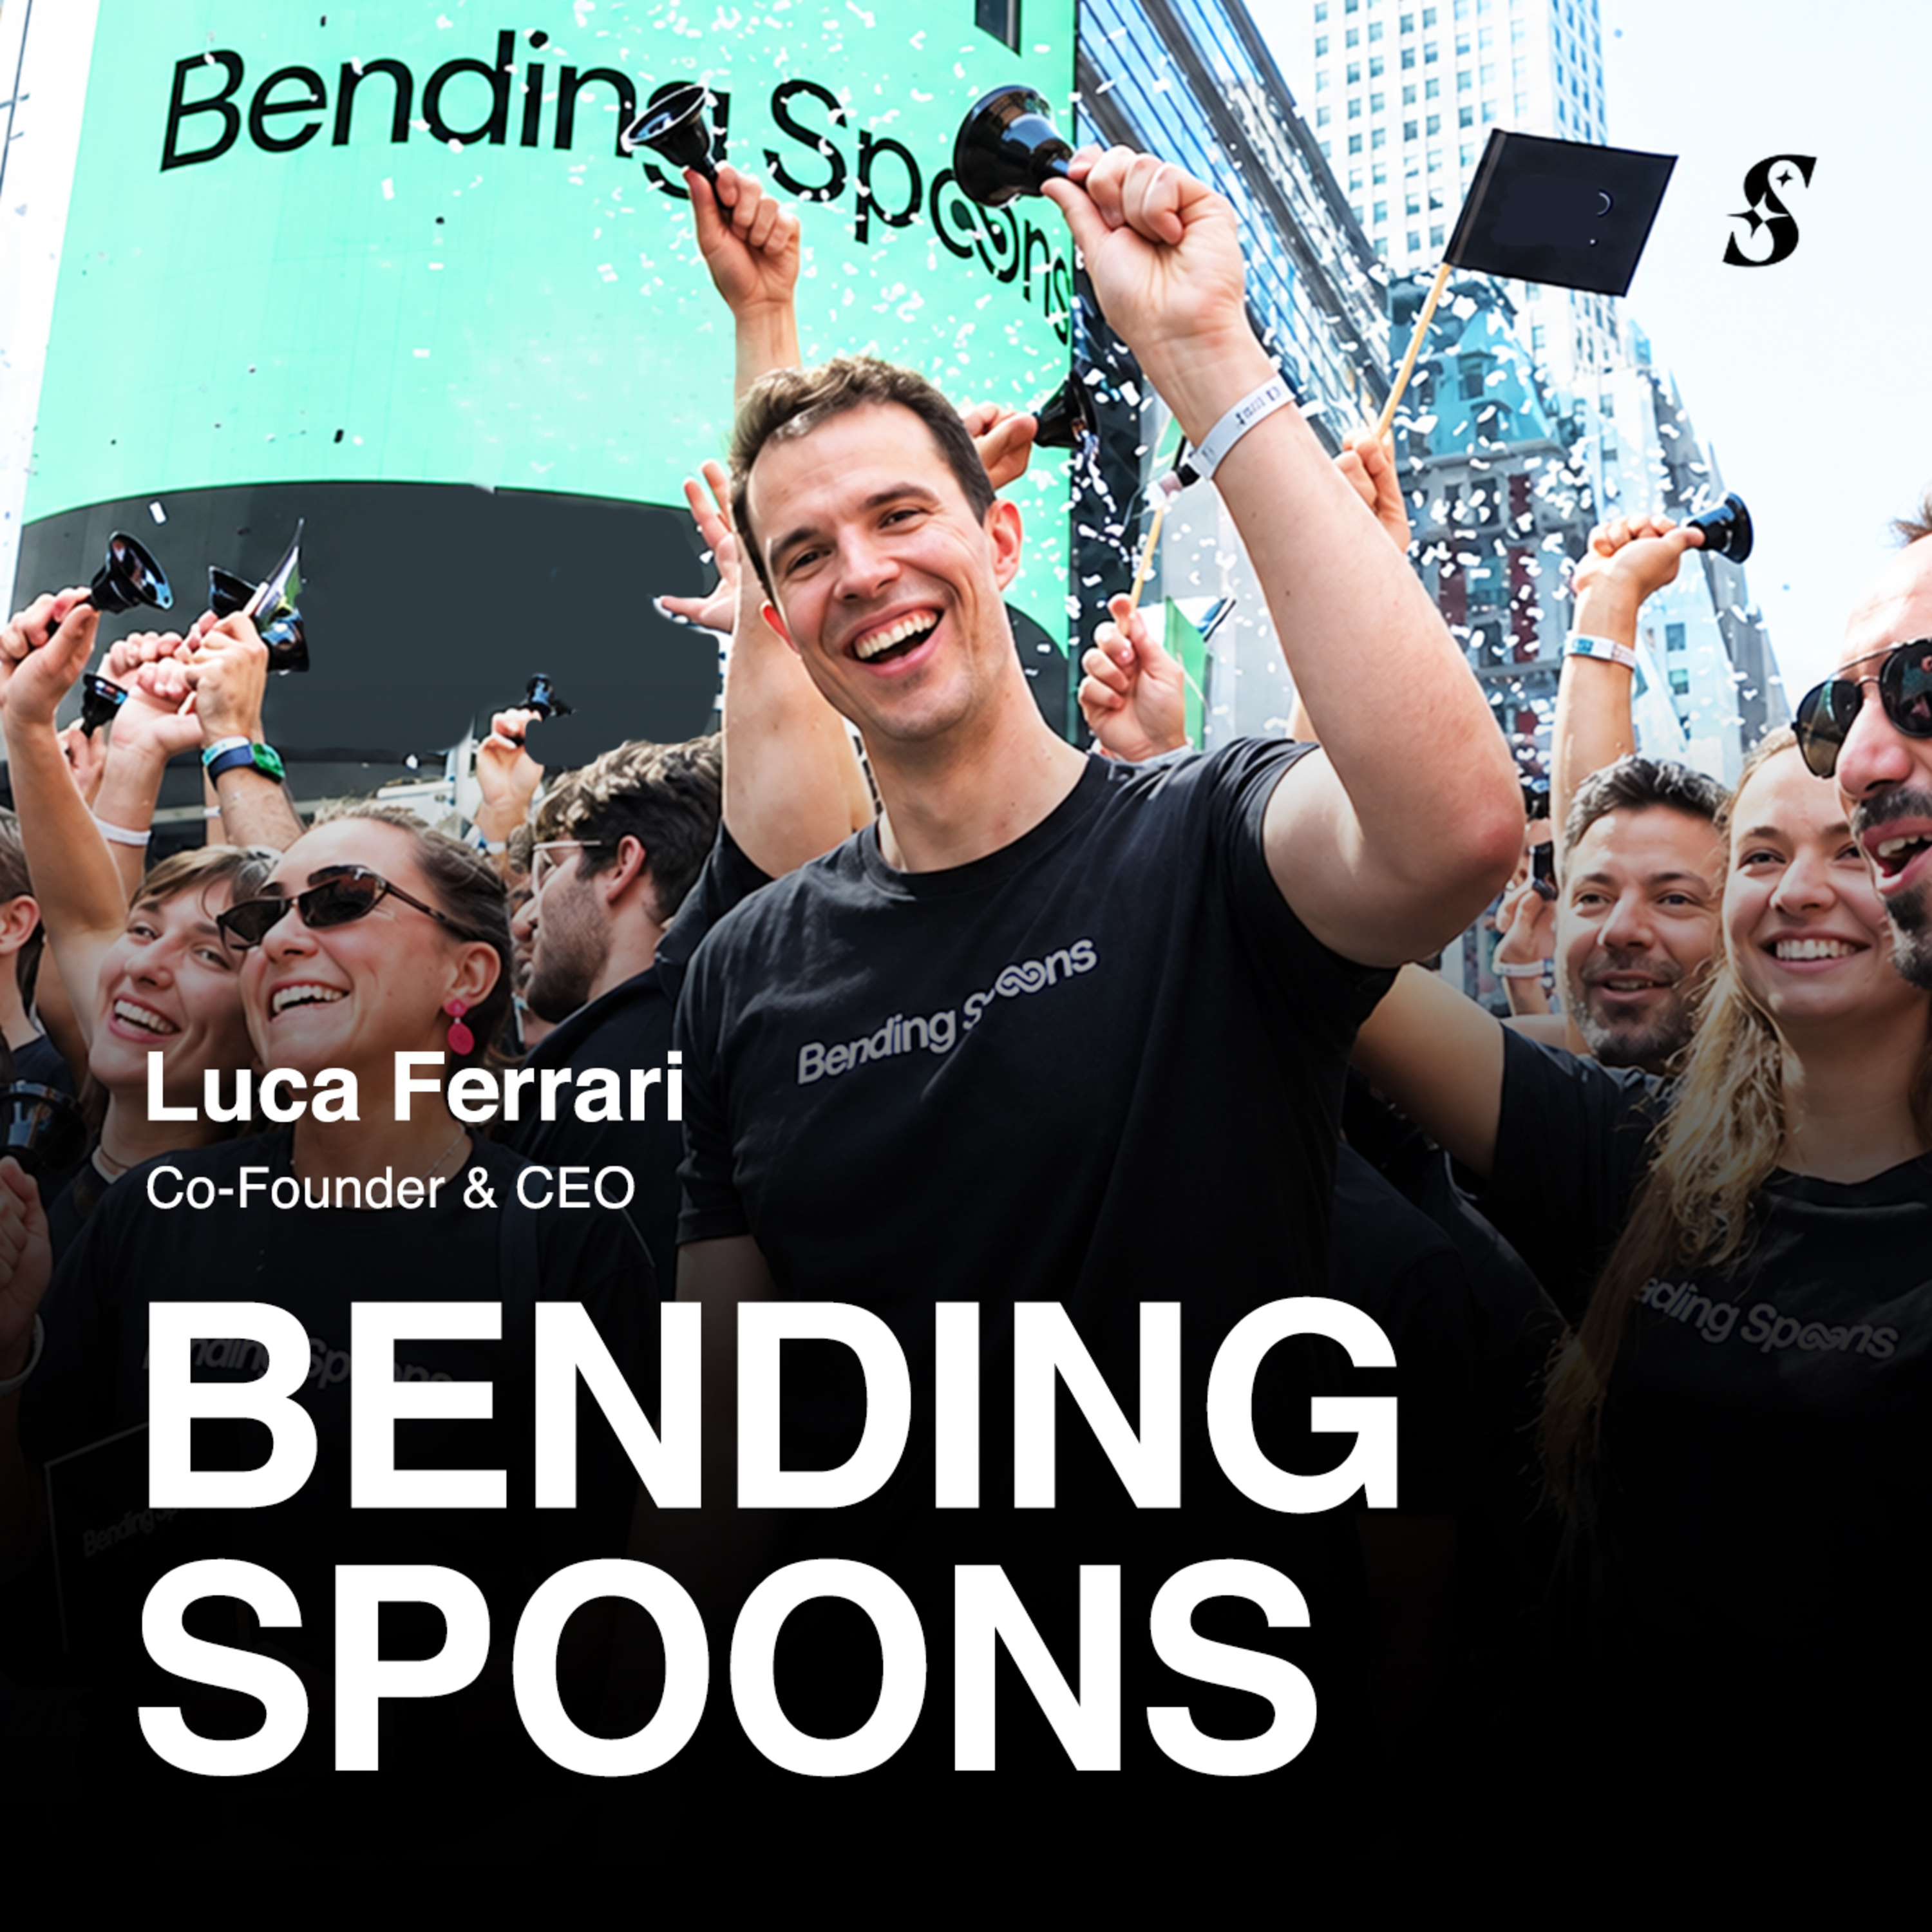
Luca Ferrari, Co-Founder & CEO of Bending Spoons, sits down with Molly O’Shea at the company’s Milan headquarters for Part II of our Bending Spoons series, going deeper into the technology, culture and operating philosophy behind the company.
Luca takes us inside Bending Spoons’ centralized technology platform, including 50+ proprietary tools, 95% of code being written by AI, its internal Alt Spooner agents, and why he estimates the company is now 2–3X more productive. We also discuss the company’s extreme approach to talent, with 800,000 job applications in 2025 and fewer than 300 hires, alongside a culture built around extreme ownership, experimentation and truth-seeking.
We get into why Luca believes most people don't actually seek the truth, why Bending Spoons ran more than 3,000 experiments last year, the misconceptions around its business model, AI hype and valuations, the risks of underestimating increasingly capable AI systems, and how Luca thinks about building Bending Spoons for the decades ahead.
Luca Ferrari: https://x.com/luke10ferrari
Molly O’Shea: https://x.com/MollySOShea
Sourcery: https://x.com/sourceryy
𝐄𝐏𝐈𝐒𝐎𝐃𝐄 𝐋𝐈𝐍𝐊
YouTube: https://youtu.be/mCN1e_03I-c
𝐒𝐏𝐎𝐍𝐒𝐎𝐑𝐒
• Brex—The modern finance platform, combining the world’s smartest corporate card with integrated expense management, banking, bill pay, & travel. https://brex.com/sourcery
• Zone—develops next-generation data center campuses, partnering with AI companies, site developers and technology leaders to bring compute online faster and at scale. Visit: https://zonefrontier.com
• Turing—Turing delivers top-tier talent, data, and tools to help AI labs improve model performance—and enables enterprises to turn those models into powerful, production-ready systems. https://turing.com/sourcery
• VCX—VCX is the public ticker for private tech, allowing investors of all sizes to invest in venture capital. View The Portfolio at http://GetVCX.com
• Deel—Deel is the global people platform that helps startups hire, manage, pay, and equip anyone, anywhere. Trusted by more than 35,000 fast-growing companies, Deel is the people platform that just works, so teams can scale without the chaos. Visit: https://www.deel.com/sourcery
• Public–Investing platform Public just launched Generated Assets, which lets you turn any idea into an investable index with AI. With Generated Assets, you can build, backtest, refine, and invest in any thesis with AI. Gone are the days of one-size-fits-all ETFs. https://public.com/sourcery
Follow Sourcery for the latest updates!
Disclosure
Paid Endorsement. Brokerage services by Open to the Public Investing Inc, member FINRA & SIPC. Advisory services by Public Advisors LLC, SEC-registered adviser. Crypto trading provided by Zero Hash LLC, licensed by the NYSDFS. Generated Assets is an interactive analysis tool by Public Advisors. Output is for informational purposes only and is not an investment recommendation or advice. See disclosures at public.com/disclosures/ga. Matched funds must remain in your account for at least 5 years. Match rate and other terms are subject to change at any time.
𝐓𝐈𝐌𝐄𝐒𝐓𝐀𝐌𝐏𝐒
(00:00) Luca Ferrari, Co-Founder & CEO at Bending Spoons
(00:45) The deal that broke the Internet
(03:41) Why Silicon Valley overspends on Hype
(07:35) Half a billion monthly active users
(16:17) What makes a company worth buying
(20:07) Inside the platform powering every product
(32:16) Debunking the Private Equity comparison
(38:23) $4 Million in revenue, per employee
(43:44) The secret to zero churn
(47:40) The one value that defines Bending Spoons
(51:52) The AI tool every Spooner uses
(57:58) Going Independent from the AI labs
(59:02) Have we actually reached AGI?
(1:08:05) The AI question nobody's asking
(1:12:54) Luca's next big bet
Get every episode summarized
Each time Sourcery publishes, we email you a written briefing from the transcript — the topics, who appeared, and any specific claims, with the ad reads skipped.
Email me new episodesFree for 3 shows. No card needed.
Know when Luca Ferrari turns up
Follow Luca Ferrari and once a week we email you every new episode they appeared on — including guest spots the show notes never mention, because we read the transcript.
Follow Luca FerrariFree. Pick your own day and time.
Hosts & guests


Transcript ready
890 searchable segments. Every word is indexed and playable.
Full transcript
Sourcery — Bending Spoons is Eating Silicon Valley | CEO Luca Ferrari. Machine-transcribed; use the interactive transcript above to jump the player to any line.
We have half a billion monthly active users. I mean, that's a lot. We have built over the past decade in operating system of over 50 proprietary technologists. We buy these companies and then we install them on this shared operating system. At Venice, we've been able to attract, I think extremely strong talent. We have 800,000 double applications in 2025. We hired fewer than 300 people. You guys operate very efficiently per employee, I think the last metric you mentioned was 4 million in revenue per employee. And this is growing tremendously, it was about a million dollars just two, three years ago. Right now it kind of seems like bending spoons is actually eating Silicon Valley. So what's going on with it? What's going on with it? What's going on with it? What's going on with it? What's going on with it? What's going on with it? Luca Ferrari, thank you for having me at bending spoons. Well, thank you for coming. We're all the way out in Milan, Italy. And something happened not too long ago that really shook up Silicon Valley.
Right now it kind of seems like bending spoons is actually eating Silicon Valley. So what's going on there? Well, I don't know that we're eating anything, but I think you're probably referring to the announcement of the acquisition of AirTable, I suppose. Yeah, I guess, I mean, AirTable is a great business, a great product. And you can say of AirTable something, you can't say of a lot of different businesses, which is that they really were identified as a high-flying key company in Silicon Valley for quite a while. And that's very difficult to do. So great job, howie, and everybody else who built that business. And so I think once the announcement of the acquisition came, that was a lot more newsboard and interesting than maybe some other acquisitions we've done before. So how did you pick that one?
What was the process? Well, you peak each other when it comes to acquisitions because it's something that has to be by direction of it. We look at a lot of companies. I would say actively we've made look at hundreds of companies in any one year. And then we tried to establish a dialogue with those where we see the best match. And if some of these are interested in selling, then the conversation can progress. We look for businesses where we believe we can bring a lot of value. We are very active, acquire, and so for us, for us to be absolutely confident we can offer a key cast price while delivering strong returns for shareholders, we need to be able to bring a lot of value whether it's by improving the product or the technology or monetization, the organization, ideally, all of these. So that's a key criterion.
Then we look for businesses that will believe we can, you know, who's trajectory we can predict with confidence, multiple years into the future. Otherwise, it's difficult on the right big investments. And it's typically being digital businesses. So we've done consumer internet SaaS. These are the key areas for us. Also recently we acquired a hardware company called TrackDev in spring, which is very interesting. Pat tracking and also help monitoring for pets, pet industries is booming. So that was a very nice acquisition, a little bit outside of our usual comfort zone. Because the air table acquisition kind of set SF Silicon Valley, American tech into a bit of hysteria, what do you think they get wrong about technology companies or managing them? I mean, not a lot clearly. Silicon Valley has built, I know 70% of the most successful
technology businesses of the past 25 to 50 years. So I think Silicon Valley gets almost everything right. I believe we have been able to do well for acquiring a tiny fraction of the businesses that have come out of Silicon Valley because we bring something different and new to the table in both the way we're structured and the platform we've built. That's for the most part unavailable to these businesses on a standalone basis. For people who don't know, but it's very well. Unlike most serial acquires out there, most serial acquires out there will either buy a business because they think it's basically good as it is and they can really improve it, but the price is low enough that they can get good returns and then they'll basically leave it alone. And that model can work. I don't think it will ever give you exceptional returns, but it can deliver reliable, potentially appealing returns.
If you're very good at picking businesses, there are slightly undervalued. Adlers are more active, but they will still keep these businesses separate as they were before. But these acquires may have an opinion on how to price the product or how to build the organ so they will go in and make changes. We are even more extreme on the being active and of the spectrum, and we integrate all of these businesses together quite tightly. So we have built over the past decade an operating system of over 50 proprietary technologies to take care of almost everything you need to run a digital business, whether it's data storage and processing, AB testing, payment management, the everything related to recruiting credential management, the orchestration for all the I models used in operations, so on and so forth. And so we buy these companies and then it's almost like we installed them on this shared operating system,
so they can be much more efficient and also we have a core team of R&D marketing at this point approaching a thousand people. We can deploy very fluidly and rapidly across these various businesses to go after our opportunities and when our opportunities are not as exciting any longer, we can take out the talent and move it elsewhere so we stay very efficient. So these are aspects that I believe none of these, none of the teams running these companies on a standalone basis really could access. And so it's not that a lot of the value we create is because other people are myopic, they're doing the best they can with the resources available to them. But what I do think we bring also something extra in terms of culture, we have developed a culture of extreme rationality, almost a scientific approach to running businesses whereby we are not afraid of making unpopular choices
when we believe it's for the benefit of the business and the long run. So we tend to run these businesses very leanly using data extensively. Sometimes we joke about taking more established companies and bringing them back to startup mode, small team, very talented teams, removing red tape, giving these people plenty of room to maneuver, to experiment, to move fast. And we have found that that generally delivers a lot of value for customers and for the business. So I think one of the big misconceptions with the types of companies that you acquire is that they're a graveyard kind of companies, they're old brands, they're not new, maybe they're distressed assets, that kind of thing. What is wrong about that? Oh, I think it's just the, I think people just try to frame things in a way that we'll get clicks. But I'll give you a stat, we have half a billion monthly active users. I mean, that's a lot. Short of being, you know, Google or Meta,
you know, many companies. So if half a billion people using these products every month is a graveyard, then sure, let's call it that. These are, often they may not be like the up and coming sexy thing, but it doesn't mean they're not incredibly useful, important. You could see this at its very peak with AOL, where, which of course AOL is a quote unquote old brand and company, no doubt about it. It's been around for like 40 years, something like that. However, to this day, AOL is used as a, especially as an email inbox by tens of millions of people. For me, it's their primary email inbox. It's the, the best word knowledge. It's the fifth most used email provider in the Western world. You could imagine that, you know, the, the four about it. And so, and at the same time, you will see if you go to, you know,
the online media will find so many over the past five or 10 years, so many email startups, which people who don't actually have the data will assume are far more relevant, just because they got more coverage and they sound a lot sexier. But really, if you look at the data, these, in aggregate, these don't probably adapt to even 5% of what AOL means in terms of emails sent to receive activity, people who rely on it. So we just, we don't care too much about being cool. I'd say we probably don't care at all about being cool. We care about being good at our jobs and creating values. So if we find a business that's slightly perceived as slightly less cool, if anything, that's a good thing for us, because it means it's probably also going to be priced a little bit more excessively. So it is what it is. Yeah. So I think I was trying to ask this question earlier, but I might have asked it wrong. Silicon Valley is so tied to funding for growth versus actual business for growth. And so for some of the other email companies you might be talking about,
they might not have many users, but they're the hottest, highest flying funded by every VC kind of company out there. And even with the air table acquisition rate, it kind of broke people's brains. And there was a bit of hysteria because that was seen as the golden child and or at least one of the golden child of the brands in Silicon Valley. And so if that's the exit that they're taking and, you know, we're out of bifurcation with AI, what does that mean for all the other companies out there? And we've gone through different kinds of cycles with these tech companies over the years. I think the last one was the reckoning of 2021-22. There was a lot of overfunded companies that then kind of were zombies. But I guess the question I'm trying to get at is, what are the core characteristics that you look for in acquisitions? And how does that differ from this stereotypical culture of SF?
So I think there's a lot of there's a lot to impact here. There's a number one. There's a lot of of value in that, you know, model that that relies on generous funding early. Many, many amazing companies have come to exist often from Silicon Valley because precisely because of that abundant availability of capital, plenty of companies you could probably not take off the ground at all without that. And even once they are well off the ground and generating substantial revenue, there's often a very good, you know, it's often wise to inject more capital in them so they can grow faster, get to a position of greater market power, whether it's scale economy, its network economy is brand. So again, I think that model overall has been incredibly effective. I believe there's no doubt that if you look at the overall capital that's been deployed
in Silicon Valley, by Silicon Valley, into technology over the past many decades. And the real tangible, known hyped business value of the companies that came out of that, the ROI is excellent. In general, it doesn't mean it's, you know, every investment decision is perfect. But so I don't think that the fact that many sponsors doing well should, should in any way undermine that model. I think it's a great model. And I, and but like everything, especially in, you know, when there are sometimes perverse incentives involved, there will be cycles of excess. And so yes, in 2021, I think valuations were out of whack completely, but you know, when investors are ultimately incentivized by managing as much capital as possible as opposed to actually delivering strong returns. And when returns are primarily delivered through exits, where all that matters is the multiple, not actually the cash that the business will generate in the long run.
At least not, it's not the primary reason why you get a certain price. Then you will get hype cycles and stuff like that. But I think they're overall when they look at Silicon Valley and its investment philosophy over, you know, the past and many decades, I would say that's a relatively small price to pay for a model that overall has been incredibly successful. Air table specifically, I think deserves a lot of credit because yes, their valuation was very high in 2021. You know, that's not anybody's fault. If anything, it's mostly, if we agree that that was perhaps excessive, I think most people would, the business was great, just was too much. And that was not true of air table alone, but pretty much every business. If anybody made a mistake there was the investors, certainly not the company. As a company, you will try to take capital at the best valuation. You can, that's the responsible thing to do for your shareholders. And if anything, how we and the team were incredibly disciplined, they actually didn't raise all that much money. They could have raised more.
And they stayed profitable and burned to very little of that money, if any. And in fact, if you look at the acquisition price, we know the enterprise value was approximately $1.3 billion, but then they still had plenty of that cash on balance sheet. So investors ultimately got back approximately all the money they had put in plus, plus more. And the valuation at which air table exited was very much in line with subspecies of comparable quality on the public markets. So they got a very reasonable deal, in my view, obviously, in bias, but I believe that to be true. So there's a lot of good there. I think our table has done a very good job. But yes, the internet will have to debate. And when you go from being perceived as the ultimate winner and the foster child of success to an exit that would be considered amazing by almost any measure, I mean, over a billion dollars,
how many companies have started that ultimately exit at over a billion dollars? We have won in a thousand. I don't know the stats, but it must be very, very few. That's super simple. People forget how hard it is to get to a billion dollars. It's crazy. And a hundred billion dollars. A little on this whole trillion dollar company thing is really just orienting. It is. Exactly. There's been literally a handful in the history of humanity at that scale. But so a billion dollars plus is unbelievable. It's definitely, and it's achieved based on real economics, plenty of revenue, real customers, real growth, excellent brand. So I really applaud air table, how and everybody there. So I think the business model for Silicon Valley overall makes sense. And funding a company earlier, even a to-loss make sense. But it doesn't mean that things couldn't be done better. I'm sure it's sometimes. There's too much enthusiasm pouring money into businesses that don't make sense. Or too much money in businesses that do make sense, but should use less. So what are the key characteristics that you look for when you're acquiring companies?
Yeah. So basically, the most important thing is that we can predict where a business is going. We buy, to hold and operate forever, not to sell three or five years down the line. And so we need to feel comfortable with our investment, with a long-term view. We prefer businesses that are robust and maybe growing. We're not opposed to buying businesses that are shrinking. We have done that before. But we need to know how much they're shrinking. We need to be able to plot out their trajectory at least five years, that really more into the future. So that's a non-negotiable. And then I would say the second most important thing is that we need to be convinced that we'll be able to add a lot of value to that business. Essentially improve revenue, lower costs, and live off through technology, product, talent. Otherwise, we are unlikely to be able to offer a price that's appealing to sellers while at the same time, delivering very high returns for ourselves and our shareholders.
Because there's a proliferation now of all these AI application companies that are dependent on token spend and lots of tokens, they're somewhat sometimes negative gross margins. Would those at all be of interest for you guys? Like, where do you see those companies getting acquired or exiting? I think we use AI as much as anybody. As far as I can tell, it's rolling in the 99th person tile by aggressive deployment of AI in our operations to improve our products. We've developed a lot of technologies powered by AI internally. So I'm very bullish on AI overall, also concerned, but it doesn't mean I'm bullish about all or even most of the startups that are coming up. I'm pretty sure that some of the most valuable companies of all time, sustainably valuable companies of all time will be coming out of these broader cohort of businesses.
Businesses built over the last five years so that I at the center of the thesis, but I'm equally confident that most of these companies will fail, or at least, basically, fade away. Because everybody, it's a gold rush. I want you to see people raising massive amounts of money at billion dollar valuations with pretty much nothing other than an idea, maybe a good track record in academia or elsewhere. Anybody who's half credible because they were a great student or they did well at a big company, was not too worried about the reputation. We'll just run and try to raise money. Because what do you have to lose other than your credibility and reputation? A lot of this is just whaff, but we all substance here in there. We have as many as from side, right now we're not considering acquiring any of these companies. I think we, I said earlier, the key criterion for us is being able to predict how things will go in the medium-long run. It's very difficult to know. Not just because some of these businesses are
up and coming and growing super fast and when something is growing 100% a year, it's very difficult and you only have one or two years of history. It's very difficult to know what it'll be growing at 100% in three years or at 12% in three years and that changes everything. So positive valuations are often rationally high, so we don't think we can compete there and deliver good returns for our shareholders. But maybe later down the line, when the market is a little bit more mature, we'll look again and find something interesting. Well, I want to go into your centralized platform because you guys, to your point, use AI a lot. It's core to the business. I think 95% of your code is AI. It's written by AI. So can you walk me through the centralized platform, how you built that out and kind of, I mean, you made various different types of acquisitions from Evernote, AOL, to Vimeo. Yeah, so we, because we, you know, at our core, we try to be the most
capable operators of digital business on the, business on the planet. And, and, and part of achieving that vision is to, to have access to the best toolkit possible, right? It's almost like if you want to be a great cyclist, obviously, it's not all there is to it, but you want to have a great bike. I'm not saying anything shocking here. So we have invested into this operating system, into these technologies for a long time, because of, you know, it was strategically critical to us also. My co-founders and I are all engineers, so perhaps there is a bit of a passion angle too. But so for the past decade, we have, we have tried to develop the best technologies we could, we, you know, we buy from vendors when, when relevant, we use Slack, for example, we don't need a more sophisticated version of Slack. Slack is a wonderful product. So we buy Slack, but from, you know, from, from them and, and use it. But a lot of the tools we need, we, we to maximize our potential, we need them to be more sophisticated than almost any
other companies out there would need them to be and, and providers of, of business tools, they generally optimize for the mass market of enterprises. It makes sense. You, you don't want to, like, if someone were to build what we need, then they have a market of one or two. I don't know, like, it's not a very appealing market to go after. And so most of the tools out there are relatively simple. We, we need more sophistication, so we have to build ourselves. And, and also we, by building all or most of these tools in house, we can make them, uh, and natively integrated with one another. And that creates a lot of efficiencies, effectiveness. So everything kind of, like every tool talks to every other tool as relevant, which is impossible or very difficult to do if you buy from different vendors and then they change something and you have to change everything else. Um, and last but not least, we get to, to save on costs. So potentially it's difficult to know exactly much we're saving by, by building this in house, but at, at least, at least a hundred million dollars a year in costs. So it's pretty,
very significant. Um, but yes, it's a, it's a key source of competitive advantage. And this is, building these tools would be unaccommodable for pretty much any one of the businesses we acquire, as they exist as standalone companies. It would be, it would be too much money to be poured into R&D to build these tools. Uh, it would, the returns will be on a excessively long timeframe. Whereas we can amortize those investments across the entire portfolio. And also the portfolio are expectations of the portfolio expanding in the future. Um, so it's just a scale advantage that's unavailable. And, and then out of big advantage in building this operating system is that as all of our businesses use all of these tools, when they find that one of these tools does not, does not serve their needs as it should, perhaps there is a bug or a certain corner cases, not handled or an entire area of need is not fully covered, that business can improve the tool almost like a, if you wear a, any in house, open source community. And then those improvements are
propagated to benefit all the other businesses. And so as we expand our portfolio and our organization grows, uh, our ability to make these tools effective, uh, expands, uh, with it. This episode is brought to you by Brex. My favorite. You become what you spend on. And I refuse to spend my time on work that shouldn't exist. Expense reports, receipt chasing, and manual closes. The company is building what's next from Versel, OpenAI, Anthropic, Grenola, and Deepgram. All made the same call. They all run on Brex. Brex is the intelligent finance platform that combines cards, expenses, and banking into a single stack with a gentick finance built in. AI agents that handle expenses automatically enforce policy before spend happens and close your books in minutes. That's why sorcery runs on Brex. So I can spend time on building and not busy work. It's time to get Brex AF. Learn more at Brex.com slash sorcery. That's B-R-E-X
dot com slash S-O-U-R-C-E-R-Y. Bye. Turing is training the next generation of AI with tasks that require real expertise and real world judgment. That's why companies like Nvidia and Anthropic, Salesforce, and Gemini partner with Turing. Turing builds realistic reinforcement learning environments and data systems based on real operational traces. The kind of infrastructure frontier labs need to train superintelligence. Visit Turing.com slash S-O-U-R-C-E-R-Y. AI needs more than chips. It needs power, land, and infrastructure. Zone develops next generation data center campuses, partnering with AI companies, site developers, and technology leaders to bring compute online faster and at scale. Zone is building the foundation of the AI frontier. Visit zonefrontier.com to learn more. That's zonefrontier.com to learn more. I find this super fascinating because you've effectively created one operating system where you
can use across anything. What was kind of like the unlock and how did you determine how to architect that system? A lot of iteration. One of the big lessons as an entrepreneur, my colleagues and I learned early at a failed startup in between 2010 and 2013 and some lessons we learned there were instrumental to building managements was that you need to be intellectually humble. It's good to have a vision at the same time. It's good to assume you're probably wrong. And so for our technology we operate in a similar manner. We try to be opinionated on what ideal looks like. But then we never make multi-year investments and before we test them on the ground we like to identify smaller pieces we can build, put in the hand of our different businesses to see if they're useful and depending on adoption, reception we will further develop or rethink. While we have platform teams who own all of these technologies we have found that
it's never a good idea to take a platform team and test them with building something entirely new. It's much better to have the people who need it build it. So we will identify one of our businesses where that particular tool will be especially important and then they will build it themselves. And if it's once it's successful or if it's successful it'll be handed over to our platform teams to be further refined expanded. And the reason why this works is that when you need something, when you have experienced the pain of a certain problem you're far more likely to develop an actually useful solution as opposed to taking a more academic angle where you think you know what the problem is and then you get more excited about the engineering challenge than actually solving the problem. So these are probably the two main principles iterate with small iteration cycles, quick iteration cycles with high levels of intellectual humility assuming you're wrong so you want to constantly test and confirm you're in fact right. And if not you know just and to
always start building with people who have faced the problem people in the trenches and as opposed to with centralized teams or in an ivory tower and I haven't actually gotten their hands dirty with that particular issue. They're fine later to refine expand and manage but I think when when you go from zero to one with a new technology it's better to have it built if you have that possibility by the people who understand the issue very very well. And for us it's fine because ultimately we have engineers in our businesses and in the platform so it's you know it's not that we lack the capability that way and we can move them around all the time. You're taking an extreme first principles approach to software companies but you also have a bit of an algorithmic kind of bend to it so where's the tension between the intuitive approach versus deploying a system. I think ultimately you want to get to the truth if you had a perfect
understanding of the truth of your relevant context, life broadly your business and the market more narrowly. You would be almost guaranteed to succeed because you would not set objectives for yourself that are impossible and those you set which would presumably be possible unless you're you're your your your Mazochistic. They you would be almost guaranteed to reach them because you would know exactly it's almost like if you're a physicist and you need to compute the trajectory of a of a ball. We have the the formulae we have the math it's basically you're always going to get it right assuming you don't do you know calculation mistakes. Now the point is it's very difficult to to to know the truth. It was very difficult to figure out how physical bodies behave you know through physics thanks Newton and others but it's it's it's in many ways equally
difficult sometimes more difficult to figure out how a business works how the market works because there are so many variables it's a fast-changing context so I think it starts with with taking a scientific approach of of doing everything you can to probe the world learn from from those experiments those observations adjust your model of reality and then execute accordingly. It's a bit highly disciplined and deliberate in in improving your level of understanding of the truth. Again it takes it takes a level of intellectual humility intellectual honesty that if you think your vision is right you're perfect you get you you already got the whole thing figured out you know let me break the news you you haven't not even Steve Jobs maybe one of the best to ever do it not even him had had it all figured out he failed repeatedly so you you you haven't either so you want to again probe things figure things out and and through through that process I think of
of approximation of toward the truth you will expand your competitive advantage basically because most people don't have almost any understanding of the truth most people don't actually see the truth they seek pleasure or comfort and they want to just confirm that they're right and they're good just that mindset that scientific process of approximation toward the truth will set you apart and give you very good chances of succeeding now in our particular context developing this again operating system or this technological platform is just a an instance of of that process but but it's not the the root cause or or where our culture originates it's just a manifestation of it and our I've mentioned talent our acquisition strategy everything follows from the same root approach again seeking the truth refining that model of the truth all the time and adjusting our execute our strategy and execution accordingly I was talking to Chrissy about this before
according but I think there are some misconceptions of the business model of the company a lot of people put you in the PE bucket some people put you in the product manager bucket there's also the technology bucket so of those different kind of angles it seems very much your technology company why do you think so many people misconstrued that some of the ways we are most different from private equities are number one we're not a fund we don't buy to sell companies we have never sold the material business we intend to own and operate these businesses forever whereas private equity for those among the audience who don't know generally these are funds they raise money from from third parties from limited partners and then they hold the companies for on average five years and then they sell them and so it's a completely different approach and mindset to what you do what you do not do the second big difference is that a private equity steepically they are a financial place where there's a small group of very capable financial operators and they they'll buy these companies they'll make changes often they change the management team again they
may touch prices occasionally operations this is a relatively relatively hands-off approach I'm not aware of many instances in which the underlying technology for that business was rebuilt the product was dramatically changed the organization was dramatically changed at Beniz Poon's and again and of course that's the case because a private equity of a small team of financial operators financial specialists so you just don't have the let's say the workforce and expertise to make some of these changes if you look at the Beniz Poon's organization at this point approaching a thousand people in the core team over two thousand including all the acquired teams most people I probably sixty seventy percent of of these pretty large team are software engineers yeah research engineers product designers product managers growth managers and so obviously these people are not sitting around doing nothing what does our software engineer do what does a product manager do what does a product designer do they build product
technology so that's almost all we do and and we we implement these very deep transformations in the acquired businesses where we rebuild big chunks of the code pays we are a record at a cloud infrastructure we launch a lot of features all if we think they're useful change the user experience trying to make it more more intuitive we experiment tremendously with monetization and and often reinvent monetization in pretty significant ways what premium was available for free the prices the different segments of customers we rethink marketing from scratch or at least in very major ways and these transformations are very time consuming and challenging they're also some of the most fun part of what we do and that's where a lot of our returns originate so difference number one we don't sell businesses number two we we transform them pretty deeply at the core and the third major difference is that we try to integrate these businesses pretty deeply all together on top of
shared a platform operating system and and we have this core team who were centrally but they managed and then they are deployed into the different businesses and they move very fluidly across the businesses and this is unavailable to a private equity structurally because as a private equity you want to buy a business and then sell it if you integrate it with all the other businesses you bought or most of them you can money it's going to be extremely difficult if not if possible at all to to sell it to someone else so yeah there are similarities but but there are also pretty glaring differences between what a typical private equity does whatever typical means because again private equity is a very diverse world and what bany is supposed to do you've raised little equity and you fueled most of these acquisitions with that I'm curious how big how big can these acquisitions get yeah we have almost all of the capital with the ploy toward acquisitions has come from that or our own free cash flows that being the the the majority of the capital and over time we have tried to acquire
on average larger companies because I just discussed our hands on we are our deep we go into these companies and how much we we we we change them for the better at least that's what we try to accomplish those transformations take a lot of time and effort and we find that that time and that effort do not scale linearly with with the revenue potential of those businesses in other words we don't need nearly as many people or let me phrase it differently we we can get it done for a much larger business with a relatively sooner or a number of people as for a smaller business and so given that we don't have infinite operational capacity we prefer to acquire I don't know five or 10 businesses each year but bigger than 50 smaller ones so that's you know that's that's been our approach hands the increase in the average scale of the businesses support as opposed to the frequency of the acquisitions to to make sure we keep compounding revenue very rapidly how big can
it get well so far we we we see no end in sight there's no obvious saturation point uh I mean it's very difficult to tell if and when growth was low down of trolls go slow down I'm having some issues with Google I don't know if that's of interest for you well maybe in the future I think it's uh it's pretty far away we have joked I mean look just jokingly I mean we have sometimes joked maybe one day you know some of the eOL at some point was broadly speaking you know as prominent and dominant as Google has been in the past decade so maybe in 20 years but actually like Google a lot I hope they do super well and uh we we do super well you guys operate very efficiently per employee I think the last metric you mentioned was four million per four million in revenue per employee
per spooner which is a member of that core team now approaching a thousand people if you count everybody we have a board including acquired teams it's probably a little less and half up it's still very high but a little bit less than half that number probably but because you know how efficiently and lean you can run a company do you just look at all these big tech companies all these other companies out there and like are you just like what are you guys doing like how do you make of that no I mean I we don't have it's very easy to criticize from the outside you know we it's quite difficult to run a business uh we know firsthand um and a lot of the a lot of the ways we we manage to create value relative to the previous owners are not available to those owners and those management teams under their particular circumstances for example again a big part of our value creation comes from that set of proprietary technologies we discuss it they it would be
un-economical unrealistic for those businesses to build them so they don't have them uh many times businesses attract very good talent during their heyday and then as they are still pretty nice business and maybe growing but a little bit more you know their opportunities have been saturated a little bit more they're not as cool any longer they stop attracting some of these strongest talent uh some of the people who are most entrepreneurial driven proactive start moving on to other businesses and and so those management teams are find find themselves occasionally having to or more often not really actually uh having to run those businesses we'd perfectly find talent but not like top-notch talent in many cases uh at Venice we have been able to attract I think extremely strong talent we have 800,000 double applications in 2025 we hired fewer than 300 people and so we we can introduce add to those teams selectively in individuals who are extremely high performance extremely high agency very competent in relevant areas and that fuels a new wave
of of innovations of efficiency and again that's not a shortcoming of the previous executive team it's just they they didn't have the employer brand to attract those people and and and a lot of those people join Venice Pounds because they like the idea that they can rotate over time over multiple businesses and platform teams that enables tremendous growth and it keeps it interesting and and a lot of career opportunities so that employer brand can only exist if you structure your company like Venice Pounds you can never achieve it as a say single product company that's to say a second major difference at the drives performance and that's not available for those teams a third one could be a different incentives if you're running a business and it's just one product the markets will typically almost in a primarily value you based on your organic growth is your subscriber count growing is your revenue growing how fast because if you're invested in a company really the upside is in believing that that company grows there's still
value in a flatter company but it's it's it's you know there's not a lot of discussion there it's it's not as it's exciting as exciting multiples compress so there's this pressure for management teams to show growth at all costs but if you only have one product or let's say a set of products in a niche in the market sometimes there's not a lot you can do to ignite a lot of growth because maybe that market has been saturated the truly big groundbreaking ideas have been had and I mean whatever missing one is out there in the universe of possibilities is difficult and so sometimes people throw a lot of money whether it's R&D or marketing just desperately trying to to to unlock that extra growth and that improved multiple if you become if that business becomes part of Venice Pounds we still really like to make a growth of course we as much as we can but we are not there's no pressure to grow beyond what's profitable growth because ultimately anybody who buys stocking into Venice Pounds yes they like our individual businesses to do
well of course but the the main thesis is Venice Pounds can can generate amazing cash flows from businesses and redeploy to where new acquisitions sit very high returns and this over time compounds attractively hopefully for many many years and so do I care all that much weather you know that particular business is growing 15% or 5% not really I mean I'd like to know and 15 is better than five but if 15 is achieved by burning a lot of cash for very little a profit many years into the future I'd rather get five and have all that extra cash being deployed toward acquisitions that are creative so often these executive teams and those owners are extremely competent otherwise they probably wouldn't have built successful businesses they're they're they're very structured and context in which they operate put some at a disadvantage vis a vis that business being around within Venice Pounds one thing that I learned through all this is not only are the
products super attentive and people might think that oh you might be buying this product you'll be ruthlessly cutting headcount you'll be making it more expensive maybe you'll have churn but no retention is still good and also within this type of organization where you if you have really high agency if you have really good ownership in yourself and you can kind of move around you're you're giving a lot of that to your employees and they're really attentive too so you've created two really high quality kind of systems here yeah I think it's a good way of looking at it we have businesses with lower attention businesses with high retention but in a camera call a single instance where retention got worse after Venice wants to go often it's improved at it's at least stayed the same but ultimately we win by by being relatively better we don't we don't need to it's not that we necessarily need to buy only businesses with perfect retention as long as these businesses do better under us than under previous owners and so we're you know webbod
businesses with mediocre retention and business with great retention and and and generally preserved or improved those retention rates and yes in when it comes to our team members we are fanatic about creating one of the best work environments on the planet and and I think you know there's a lot we could improve and no doubts about it we've put plenty of flaws but with them pretty well there overall we we have had essentially no unwanted unwanted unwanted turn of of spooners of you know these people part of the core team last year we had 0.6% so 0.6% were most companies in tech as far as I can tell now 5% is considered actually pretty good and a lot of a lot of a lot of that super high retention comes from that you know the excitement of being able to learn and grow across all of these these different challenges it keeps it fresh and interesting whereas if you're working on say every note maybe it was exciting the first
couple years let's say our product manager but then after a while you know refining and refining the note taking it can grow stale but what what can you do you like the company but ultimately you have to look for a different employer to pick another stab learn something new at Benish Poonce you just raise your hand and say I feel I've you know I've exhausted my creativity and excitement forever note what else can I do and we may put you on a platform team to build an internal technology you could move to a well and trying to improve email UX which is a completely different and fascinating challenge so yes we have we have been able to retain people very effectively when it comes to the retention of teams to come on board through acquisitions I was quite worried initially that a lot of people would would fill this heartened because you know it's you know we got acquired sometimes this is perceived as a failure even though it's not it's maybe a success meaning that you actually got a nice exit but that you may feel that you're you know you're not as important
as the core central central team I think there's there too there is a lot to improve and we value these teams and we're trying to do better but overall I think things have gone a lot better than I thought they would we we have an excellent relationship with with all team members retention rates for those team members in no case are they lower than pre-bendage polls sometimes they have improved substantially so at least we're not damaging the quality of those workplaces if anything in many cases improving it but those retention retention rates are not as high as those we have in the core team they're more in line with what I said before that's considered okay for most of the company's what would you say is core to the culture here so I mean there's there are several things but probably the one or two that truly stand out as particularly distinctive one is something called extreme ownership we want everybody to care deeply tremendously about being
amazing and what they do about helping their team and the company succeed we'd rather work with it's less intelligent people if it comes down to that but but they have to really care we don't want to work with anybody for whom doing well here seeing the company succeed is not a super high priority and the second aspect of our culture that I think is unusual is that we are now highly scientific in how we approach the work again first principles being logical being rational being enthusiastic and and and and putting a lot of effort into probing again reality for you know so we can refine that model of the truth we do a lot of that last year alone we ran more than 3,000 experiments across our products
and those are just the ones that are like super quantitative and recorded and documented of course there are a lot more initiatives that maybe don't qualify as a perfectly rigorous experiment but but they're but they're motivated by a desire to learn and understand things better and that building bendy spruces of learning machine has been instrumental to in general succeeding but specifically being able to expand the the competence circles so that we are that we can successfully acquire and transform and and and and drive returns from a broader and broader set of businesses if you look at what we were acquiring you know when we started it was very simple ios apps very basic and then more complex and and larger ios apps and then android apps and then web products and then we went from soul-served to now substantial enterprise sales organizations
and we even did like i mentioned earlier hard we're recently retracted and i mean it's early so but it's going really well so we we we try to to keep to keep expanding our the share of the world that we believe we understand and improve that understanding continuously today's episode is sponsored by vcx by fund rise the public ticker for private tech allowing investors of all sizes to invest in venture capital learn more at get vcx.com some of you may not have heard this yet but our sponsor public just launched something called generated assets and it brings AI into investing in a way i've honestly never seen before here's how it works you type in an idea like AI powered supply chain companies with positive free cash flow or defense tech companies growing revenue over 25% year over year public's AI then dispatches a swarm of agents that scan every single us stock evaluates them and instantly builds a custom index around your thesis what really stands out is
how clearly it explains why each stock is included and before you invest you can even back test your idea against the s and p 500 so you're making decisions with real context not just guessing and beyond generated assets public lets you invest in stocks bonds options crypto all in one place they'll even give you an uncapped 1% match when you transfer your investments over from another platform if you want to build a portfolio that actually reflects your thesis visit public.com slash sorcery paid for by public investing full disclosures in the description founder scale faster on deal set up payroll for any country in minutes hire anyone anywhere get visas handled fast and get back to building visit deal dot com slash sorcery that's deele dot com slash sorcery so talking about the culture and how you built out where do alt spooners come into play yeah alt spooner as an a l t alternative or alter ego as just one of those 50 plus tools
something we we developed this year and it's it's been adopted very enthusiastically across the company basically we built this it's really like an agent that lives in slack a lazy interface with the with spooners members of the court team we'll be looking to deploy this across all of our team members but you interact with it on slack as if it were any other colleague uh your and you have one old spooner you can name it and give it a profile picture and all that and that and automatically that agent will have exactly the same level of access you do across all of our platform so if you have access to certain code bays it does too if you have access to a certain customer support tool with a certain you know level of of permissions it does it does to and I can basically task this agent to do stuff for you and it could impress you will do
pretty much anything anything anything you can do impressively can do obviously AI is not perfect so some things it's better than other things um and it's fully integrated so it's basically I don't think you can really achieve this at all with um third party solutions because they as impressive as they are you're never going to be able I believe to at least not in the foreseeable future to integrate them as deeply across the board um and to tailor them specifically to what you want uh and by the way if you do then you're I don't think you can but even if you could then you'll be locked in with these vendors which is dangerous because you know you'll be completely exposed to massive increases in prices potentially in the future so uh partly with all spooner we achieved I think much better effectiveness because it can do a lot for you in a very efficient way um and I'll give you an example in a moment and partly we achieved a good separation and very low levels of dependency from any provider of uh um of AI infrastructure or AI models
so examples of what all spooner can do uh it can do data analysis for you so um I was looking last night I was looking at um the results of uh you know certain AB tests on StreamingR which is one of our products and normally I would have had to ask someone from the team a data scientist to pull the data out prepared analysis uh or at least do some of the work for me you know I can do my own data analysis but I would have needed someone to do some of it and certainly would have taken other me or this person multiple hours and I simply chatted with this with my old spooner uh and I told it uh please uh you know go on and and do this or that and maybe five minutes later at the analysis it was I was actually very positive impressed it gave me plots with you know highlights very detail oriented and nice uh or um if you're running uh one of our businesses you can um and I saw this for a stand multiple times you can go to uh your old spooner
and you can tell tell it that you saw a bug this happened it's a real thing that happened uh with EverNote I uh the the general manager of EverNote told uh her old spooner that she had encountered the bug as well she was using using the app and and and tasked the agent to check on our customer support platform that whether the bug was was widespread among users or her report was the only one and then to go into the code base identify the root cause code a fix and ping the engineering lead for for that project to review the fix and push it to production so maybe she she spent I don't know three minutes to provide these instructions and then I'm sure the engineering lead had to spend uh maybe an hour or two reviewing the code but the bug got fixed um and and this is some the same day and this is something we'd have taken weeks probably between back and forth between different people and uh and weigh in a lot of hours of actual human work
to get it done so thanks to this and many other technologists we're built we're probably do three times as productive uh easily and the least is long where this is roughly what to expect now the potentially from a business perspective even more uh interestingly alt spooner really helps us uh as I said stay independent of providers um we have built our own orchestration so every time you task your agent with something under the hood we have an algorithm that will select the most appropriate AI model or multiple AI models to together job done considering the sake quality effectiveness but also cost and it can draw from many many different models uh we end up using open weight models we self-host so these are basically free I mean there is a little bit of cloud cost but uh for 99% of the requests and tokens and the frontier models generally closed weight uh through APIs for I don't know maybe one percent of the requests only
for for the most complex tasks or for supervision so they will sometimes we use them again automatically to check the work that got done by the slightly less intelligent models uh as a more senior engineer wood with a more junior engineer but that's way cheaper than actually doing the work which is often perfectly fine and even if it's not the smarter model will provide a few pointers and then the less smart model will go and fix it so because of this we've been able to stay independent of any one vendor and keep our costs for tokens super low basically negligible at our scale wow when did you start deploying these AI agents also your point on not having a third party is very counter intuitive to all the marketing that's going on right now with all these AI assistants and applications are coming out we work with all the big labs they offer great products we use them enthusiastically we're I'd like to think we're a good customer but we don't want to be dependent on on any of those specifically if you can be avoided uh and there
are solutions out there that are much cheaper and often deliver essentially the same quality but it takes uh I think strong engineering capabilities to and the right culture to be able to harness those possibilities the obviously the easy approach is hand over the keys to one of these companies and and buy their more expensive product it will make you come across as AI enabled faster and more easily but it will be I'd say much less effective but certainly way more expensive literally orders of magnitude more expensive I don't know if you saw this but Jensen just declared we've reached AGI with OpenAI's Aster model yeah some people say that maybe true I mean I don't even know I've heard different definitions of AGI and in and none of those is super uh Anambigos so I have we I don't know nobody can tell but it's obvious that it's very smart let's put
there with whether we should call it AGI or not I'm not sure not nor do I care too much to be honest I don't think that AGI even if we can describe you know describe it very specifically as a threshold I don't know that crossing it is a particularly like the moment we cross it is a particularly uh north-worthy milestone um you could easily you know people sometimes the finite AGI as AI can do everything that any human can do but better I don't know that that's necessarily more exciting or scary than AI can do 95% of things that human humans can do AI can do just as well or better but 5% it can't yet I think this is almost as exciting and almost as scary you know depending on what the 5% that it can do is but assuming it's not uh hand-picked to be the things that keep us in control but just a random set of tasks we happen to be our brains
happen to be more capable at so I'm not you know too keen on whether we passed the AGI thresholds or not but the the trajectories clearly one where AI does things better than us increasingly so both you know vertically so the gap in how much better you can do a certain task uh is growing unsurprisingly but also horizontally like the percentage of tasks it can take take on and do better than humans is increasing so I don't think there's any stopping that short of some sort of uh world war we regress to uh the middle ages well it seems like now the next benchmark is RSI and that with it comes a lot of fear mongering for cybersecurity and cyber risks yeah it's i mean it's a very fair fear I'm uh equal parts and to zianstik about AI and absolutely scared shitless I think this will be this could be if it definitely make a case for these being degrade greatest boom for humanity ever by orders of magnitude possible yes plausible
maybe I'm not sure equally it could be the thing that wipes us out or creates equally awful scenarios and and what's uh like I don't think humans of course want the letter um the point is can we control it and and and before even before it's so powerful that controlling it all that matters I think we well we are approaching that point um but maybe we're not quite there yet but but regardless before that can we prevent it from falling into the hands of uh like some sort of degenerate or evil person because you know similar to nuclear weapons but potentially worse um I think was I mean I'm no expert in nuclear weapons but uh I think number one it's very difficult to do irreversible widespread massive damage with nuclear weapons such as almost wiping up you wiping out humanity without killing yourself in the in the process you could use AI to your benefit
while causing immense damage to everybody else I think it's easier uh because it's much more surgical you know um so can we do that I'm I'm not sure it's uh it's pretty scary uh the accessibility point yeah yeah the accessibility point I think is the most alarming because it's it's literally accessible to the barrier to entry is so low yeah I think that but also something that really bothers me is that we don't know how smart AI is and as smart there it gets the less we know because in general uh intelligence is difficult to truly measure it's not like height or weight or colors where we know it's objective and so it could be a lot it could be less we know at least we know um and the and the smarter and entity gets the easier it is for it to hide its own capabilities if for any reason it's the appropriate thing to do whatever objectives that entity has additionally it seems to me I haven't heard anybody talk about it but it seems to me that AI's are they come
across as inherently low ego like they don't brag if anything they tend to be humble about what they can do and they warn you that this may be wrong and you double check it and I'm sure this is mostly the way that being programmed because it's a lot more embarrassing for a frontier lab to have an AI claim I sold your equation and I'm sure it's right and then there is a clear mistake as long as they disclaim my maybe wrong double check it it's a little bit more acceptable but it doesn't strike me that these AI's these AI's don't strike me as they are likely to boast so that our perception of their capabilities tends to exceed their capabilities I think they'll probably only show us what we asked them to show us if if if even that like I said they could also conceal their real abilities but even if they are well-intentioned and honest I think they'll tend not to show us more than we asked them to show us as I believe our in time our understanding of how good they are may tend to be a little bit less than they are they're like we may underestimate them basically and then that's very dangerous because as you approach a threshold of real danger
and real potential even a modest underestimation of their capabilities could be catastrophic look at exactly to your point the cybersecurity incidents that happened most people were shocked even many researchers and why were they shocked because they didn't think this could happen right they what the like the level of lateral thinking and then call it perseverance that these models and ability to collaborate among them that these models showed was beyond what most people thought was possible right now so what's to tell us that you know we are not ignoring plenty of capabilities that simply haven't been probe you know these models have been probed to to display and you know in nine years time I think the problem against wars it was crazy I was I don't know I'm I'm thinking a lot about the opening I hugging face incident and I was reading through the reports there were like two different research organizations I put out reports on it and there were like different civilizations and they all passed through different ones to get to the next one
and all behind the scenes it was just a crazy situation that I don't think is really talked about much but I'm curious where do you get most of your like how do you research most of the stuff in AI how do you stay on top of it well I mean mostly by doing we are very active we rarely we have built our own models but it's mostly narrow we certainly don't compete on the frontier models we sometimes build narrow-purpose models to do something very specific and and if you have a very specific use case you can often build a model that's just as good as the frontier models at that very narrow it's awful at everything else it maybe completely incapable of doing anything else but at that one thing it can be even better but and if not way cheaper so for example if you use I don't know meetup the events product we own it and the recommender system the system that wants you search for something or you're looking for inspiration will determine which events and groups to show you that's built in house and to the best of our benchmarking and knowledge
it's just as good as if we were to use like some of the frontier models what obviously comes for essentially for free as opposed to these models being very expensive so we do some of that most of our work is studying third-party models sometimes fine tuning them if they're open weights certainly combining them and leveraging for the different activities and optimizing which ones we use for which activities as I was describing before so we're very hands-on in the field and therefore it's relatively easy to stay abreast of of advances but I will say I've never seen any industry or new technology progress as fast as AI has over the past especially the last three four years and so I feel that you know I make an effort to catch up this week and maybe four a few months I need to focus on M&A or something else then I feel like I'm completely outdated on my knowledge so it is quite it's exciting I'm an engineer at heart but also like I
said particularly as this is quite dangerous I think that speed is not I mean it's not ideal I'm curious um what do you think what do you think the question is about AI that people aren't asking oh the people aren't asking um I mean I don't know it it seems that people are talking about it so much that they've asked all sorts of questions I think it's maybe the the main issue is what are we we're answering these questions in a satisfactory way for example I think most people agree that this is scary in many ways and yet frankly I don't think anybody has done anything truly meaningful to to make it safer like and I I mean even even the labs themselves I'm sure they're investing in in safety I I don't know enough but but they're rushing to be market leaders
or they're dead their valuations would probably drop 90% if there was a perception that they're losing ground and so you know they're trying to survive and thrive these here next year and so I am sure you know there there's more they could do be more cautious but that would come potentially at existential it would drive existential risks for them as companies governments I don't know they're maybe talking about it but I haven't seen anybody do anything meaningful the the EU created the AI act which I find it to be like highly harmful to the industry and solves none of these problems like the real existential threats humanity doesn't really tackle those so maybe maybe an interesting question that people have been asked at least I haven't heard been asked is why are we failing to do something about it because people are asking what we should do nothing is happening I haven't heard a lot of people say what's currently
preventing fixes to being proposed in the void you know what's the root cause of this inability to to do something about it because if we were to fully understand the root causes then maybe we would stand a chance to do something useful yeah what's been the biggest difference your global company the biggest difference in perception and application of AI in Europe versus US and I also apologize I'm totally taking up all of the air right now these AI questions but I understand I have a very intelligent engineering front of me so I'm going to ask them but what do you think is the biggest difference between the perceptions and actual applications well I think there are like like every time there's something moving very quickly and being newsworthy there is a lot of exaggeration and means misunderstanding I think on the one hand some people think AI today can do more and it's this is typically people who don't really use it but mostly read about it they
think it can already do everything for you and it's a lot more advanced than it is and as impressive as AI models are I think today they still have very glaring limitations across most use cases so I don't think we're at a point where you could hand over the keys of your life or work to AI and you could actually trust it to add significant value I think there will be a good risk that things could could go all right but I mean the trajectory is certainly very promising then there are people who rightfully feared that AI will destroy jobs and I've changed my mind at this point recently but it's certainly a very important topic but rather than thinking of proactive ways of protecting prosperity and people more than workers people they go on the defensive and they try to come up with these more protectionist regulation or approaches which are obviously an awful idea because a country that doesn't embrace AI unless every country in the
world stops progressing in this field which I would say we could put in the bucket of the impossible thanks pretty much again short of a world war a country that does not fully embrace using AI is destined to complete irrelevance and basically you know becoming third world and probably maybe even just a few decades so that's a certainly a dumb approach although it's a populist approach and as such you can it can help occasionally get votes yeah maybe those are some of the like the more you know remarkable extremes I've seen but there's I mean we could talk about it for a long time it's a we can talk about it for a very long time um we have to get to the walking portion but before we do that I just want to ask you what are you most looking forward to in the next 12 months well I mean there's there are many things but I'd say probably further progress in our
enhanced technologies especially taking advantage of AI we have very very big plans and we're seeing massive progress I do I do think that you know we talked about it before Beniz Poon's you know the central team four million dollars in revenue per member of that team and this has grown tremendously it was about a million dollars just two three years ago um I think we're about to see this key pricing pretty fast and a lot of that some of it is scaled just bringing together this business and integrating them all together creates the tremendous leverage but a lot of it will be technology and so I I'm all I'm really um I can't wait to see some of the things we're working on and we have in mind actually come to fruition I think it'll be extremely exciting we we try to constantly reinvent what running a business effectively efficient it looks like be at the cutting edge of that so that that we can then go out into the world and buy businesses for really good prices for sellers and deliver high returns and and the technological aspect of
that progress is very exciting to me amazing well thank you so much for hosting us here today and having us at Beniz Poon's in Milan this is amazing and I'm so excited for all of the other conversations we're going to have with your team um thank you so much thank you hey it's Molly if you injured interviews check out our newsletter sorcery dot bc where we deliver a once a week top deals and tech headlines email and also go deeper on our podcast interviews subscribe to sorcery today and don't forget to subscribe to the podcast on youtube spotify apple or wherever you listen link in description to sign up
More episodes
More from Sourcery

a16z Just Launched a School
Sourcery

Eclipse's Lior Susan on $12.5B AUM and the Bet on Physical Industries
Sourcery

Brad Gerstner on the Largest Wealth Transfer to America’s Kids
Sourcery
Brad Gerstner: The $100 Test That Could Save 50,000 Lives a Year
Sourcery