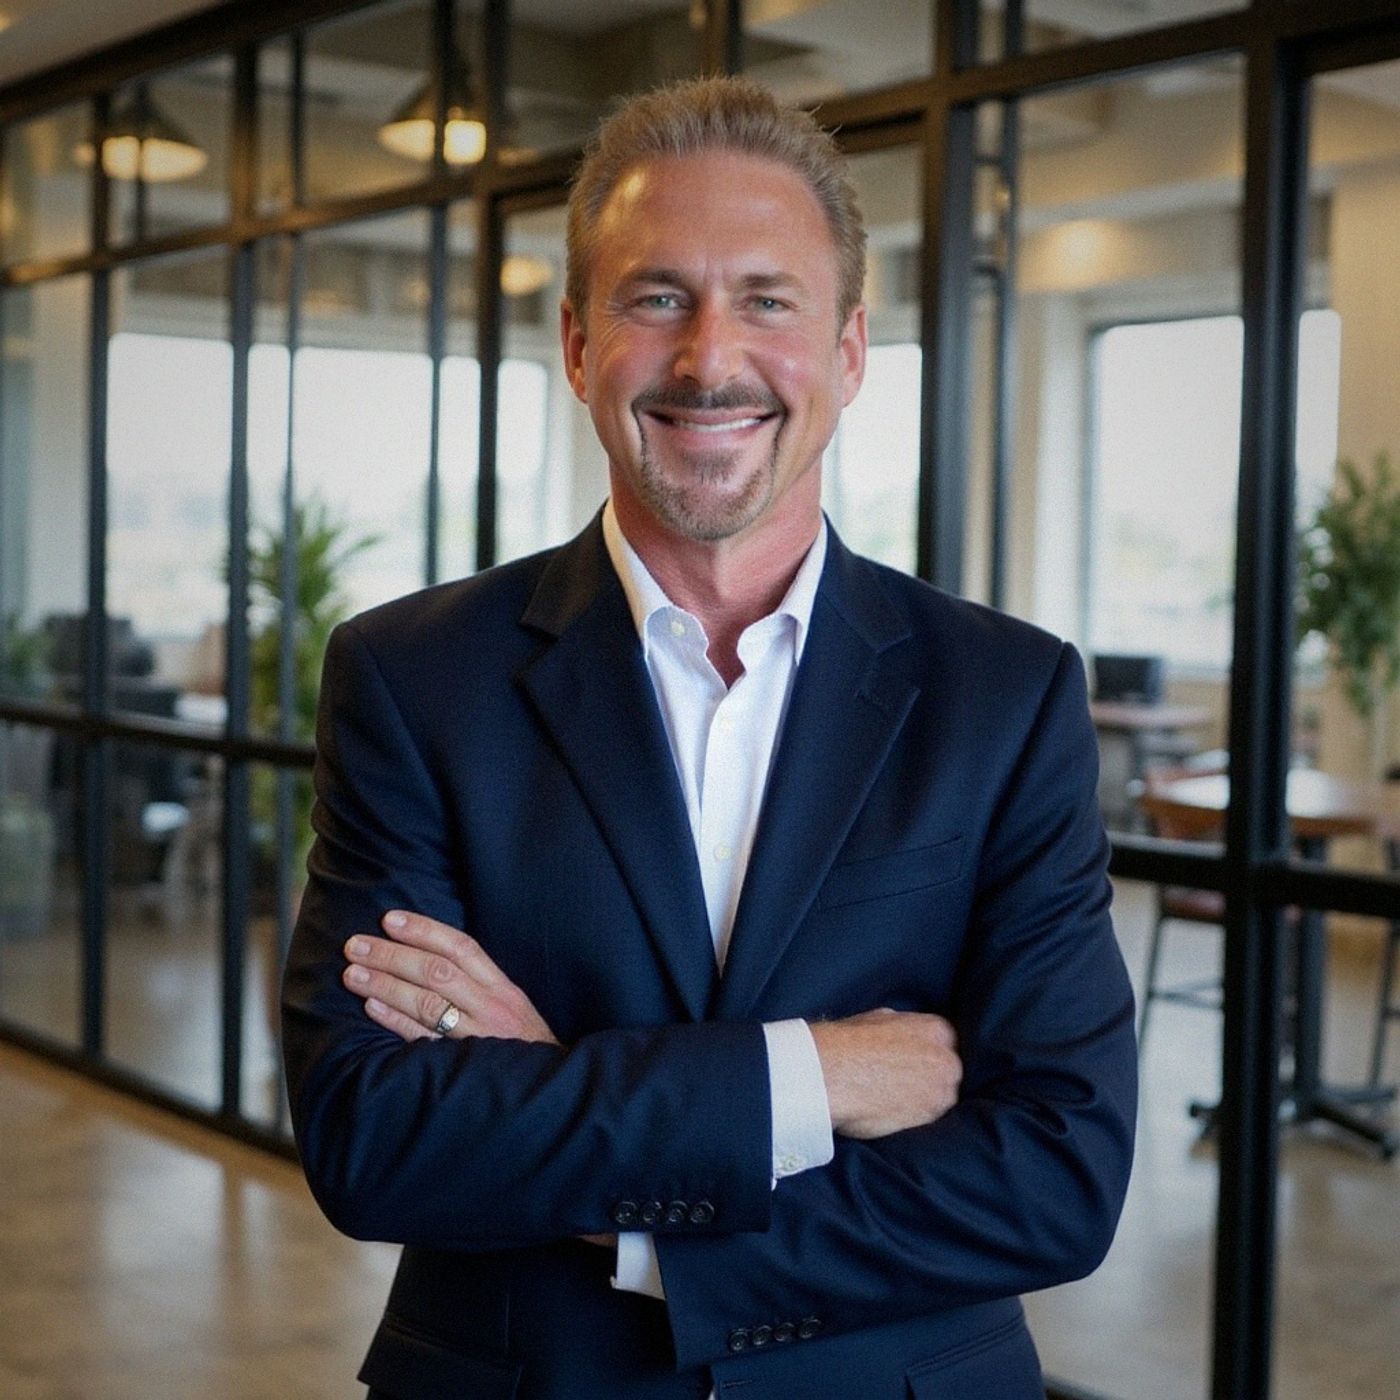
"Zero is Your Hero: Redefining Retirement with Lance Mays" and Your Host Fierce Manson
About this episode
Through relatable stories and straightforward advice and examples, Mays explains how traditional "defer, defer, defer" advice traps retirees in higher taxes and unnecessary stress. Instead, he introduces the Three Phases of Money and the Three Bucket System. Showing you how to reposition savings from taxable and tax-deferred accounts into sound tax-free vehicles.
You'll learn and understand why taxes are "on sale" today, how to convert wisely before potential tax changes by 2028. How to protect your wealth from inflation, government regulation, and the largest unknown - long-term healthcare costs in retirement. You'll learn strategies to safeguard your estate from all of these potential pitfalls.
https://www.barnesandnoble.com/w/zero-is-your-hero-lance-a-mays/1148602309
Become a supporter of this podcast: https://www.spreaker.com/podcast/the-fierce-female-network--6418822/support.
https://mydeals.page/eqih
Please click on the Supporter's Group to inquire about these services: Play your music on a syndicated radio station, Play your music on a station for 3 days straight, 30 minute radio interview. For artists who are interested in taking their music to the next level join the Supporter's group for group coaching sessions!
To receive special discounts on select products shop with The Fierce Female by clicking the link below!
https://mydeals.page/eqih
Get every episode summarized
Each time The Fierce Female Network publishes, we email you a written briefing from the transcript — the topics, who appeared, and any specific claims, with the ad reads skipped.
Email me new episodesFree for 3 shows. No card needed.
Hosts & guests
Transcript ready
1,008 searchable segments. Every word is indexed and playable.
Full transcript
The Fierce Female Network — "Zero is Your Hero: Redefining Retirement with Lance Mays" and Your Host Fierce Manson. Machine-transcribed; use the interactive transcript above to jump the player to any line.
you Now listen to the Fierce Female Network. Welcome, welcome, welcome to the Fierce Female Network. I'm your host. Fierce, messing in today is Tuesday, Tuesday, Tuesday, Tuesday. Tuesday, baby. And we're going to get one down with it. Have some hot information for you, my darlings. Listen, listen, listen, I have a hot author here on today's land maze. Hold on, hold on, hold on, hold on.
I'm going to get to it. Put your hands down, put your hands down. Put your hands down. No, it's not a calling show. It's not a calling show, but where I'm going to get to you. Hold on, land maze is here. Listen, listen, listen, listen, it is Tuesday. January 6, 2026, it is 4.30 p.m. on this interest standard time zone. And 5.30 p.m. on Eastern Standard Time Zone. Yo, no, but I'm going to stay up in here. The Eastern Standard Time Zone is the time zone. There are rocks, my socks off hunting. You know I got pushed up to the ATL. That's my home team. Gotta give a shout out to them. Fierce Nation International as well. They are the hardest working team on the planet jobs. Listen, I'm excited. I got to jump all the way in here. You know, Lance, I'm going to jump into this. First of all, let me introduce Lance. Y'all know when I get excited. I don't know how to down down to zero. I live on 100. You know what I mean? I live on 100. I do. I live on 100. Listen, guys, I have Lance Mays. The author of Zero is your hero.
Mays redefines retirement with insights on tax-free retirement income, health care and financial growth, empowering readers to achieve a secure and stress-free retirement. And this is the man I need to be talking to. You know, I need to be talking to Lance because listen, Lance, I'm not going to lie. My whole audience know I'm very transparent. My financial world got all shook up. So listen, I'm at ground zero. And you, the perfect guess I need to be talking to right now. I got so much back taxes. I owe IRS. I am crying right now. I'm not lying. I got a letter. IRS is going to hunt me down. So I don't want them to be owning my sock shoes and my wigs. So I can't have that. I cannot have them. So tell me about your book. Tell me about your book. I think it's just phenomenal. The title caught my attention. I looked at the trailer. I say, this is amazing. Tell us a little bit about the book. And why? Why you wrote zero is your hero.
Thank you. It's nice to be here, Ferris. I was drawn to your show because of one of the biggest problems out there in America today is the problems facing women, especially if they have become divorced or singled or widowed. And they don't have any idea of what to do financially for themselves. This book is come about from the 40 years that I've been in the financial services industry. I've worked with people with 10,000 in their account to 10 million in their accounts. So it's not about that. It's all about making sure people understand it doesn't matter what you make. It's about what you keep and what you do with it when you have it. And the most important thing is to realize that five years or not, you're going to be what? Five years older. Now, you can either be five years older on a better path
and looking towards a more secure future financially and a more secure retirement for a person. The taxes are definitely issues that you want to address and take up with them. There's a lot of different companies out there that'll work with the IRS. The IRS will work with you directly. They'll do an offer and compromise. They will try to get something worked out with them so you can get on their good side as some kind of payment plan or something. And then focus on trying to work on what's going to happen five years from now, 10 years from now, 15 years from now, and the kind of money that you're going to need for yourself and the way you're going to be able to access that money. Basically, and I don't care who you are, there's three stages of money. You've got the accumulation stage, you've got the preservation stage, and then you have the distribution stage. And throughout our lives up to age 55 or so, we're working on the accumulation stage.
Then we work on preserving it, and then we look at taking the most tax advantage way possible in a retirement for ourselves. And again, if you're single, these are things that you really need to look for yourself and plan. My whole career has been planned on the what ifs in life. I always look for what if this happened, what if that happened, what if I'm suddenly this way. And so that was the reason I was in such demand. Again, I've spoke all over the United States. I've had a national radio show for over 10 years, five days a week. People would call in and ask questions. And as I started to wind down my professional career, everybody would still reach out to me and go, hey, what about this? Or, gee, I need to do this. Or what should I be looking for that? And I was the lifesaver for everybody. And that's what I said, you know what? I'm just going to write a book. And then here, read the book, invest 15 bucks in your life
in your future instead of spending 15 bucks on a latte or whatever it may be in somebody's life. This is information that'll stay with you forever. And information that will change your life forever if you take the time to read it. You don't read it like a novel. You read it with intention. You have to be able to look at it, read it, understand it. And by the way, it is written at a very easy to read level. I wrote it so that my mother could understand it. Because most people, when they start hearing things about financial, they kind of like their eyes glazed over and they go into some other place. So that's why I wrote the book. That's why I'm very passionate about it. You can see it. Zero is your hero. And it's on Amazon, Barnes and Noble, Google Books, there's 100 places out there that it's out there. And in the back of the book is actually an email
to get a hold of me directly. And I get emails all the time from people that purchase it. They read it. Then they usually reread it again. And they say, I need to order about five more copies because I want to give this to my children. I want to give this to my grandchildren. Because this is information that you've never been told before. So that's how the book came about. And that's what I'm doing. Speaking with you, trying to empower other people to start taking control. And whether you start with zero and then work your way up to become any hero, this book will help you. Wonderful. I have another question. When it comes to insurance, you know, a lot of people, they have a side, I guess business. I can call it a call center. Oh my goodness, 15 plus years with the call center. I took a lot of calls for insurance people. And it just really sends my heart to say this lands.
I got a lot of calls from people 80 years old trying to take out a policy at 80, 83, you know. So speaking to audiences from the 20s to, I say, 40. Now I have another insurance broker. He talks about living benefits and not insurance where you're taking out a poly just to die. Now what is your perspective and your view is when it comes to insurance? You bet. It is the single greatest thing that you could ever put money into. And let me address that from two points. If you own a home and something happens to your home, you have insurance. You know that the ABC insurance company is going to be there and write you a check to make everything whole. They're going to replace your dwelling. They're going to replace your clothes. They can't replace your memories. But they'll give you money to be able to make new memories.
So that property and casualty type of insurance is a wonderful thing to have. The other really wonderful thing to have in conjunction with that is people that actually sell the correct type of life insurance. In chapter five of my book, I talk about something called a LERP, L-I-R-P. And it's a life insurance retirement plan. And these are specialized indexed universal plans that money you put in grows, accumulates, and then grows more and more in a triple tax deferred environment. All the same while they have a death benefit attached to it, all the same while these particular plans allow people to use something called a living benefit if you become sick, hurt, or disabled. Now let me back up a second.
Between now and the time you choose to retire, anybody watching this, anybody listening to this, there's only three things that will happen to you. Between now and some point in the future. Number one, you die. What happens then? Are you young that you still need to take care of your family, your children, your spouse? Most people probably do. Especially in the demographic, you just talked about the 20 to 40-year-olds, even 20 to 60-year-olds. If they die prematurely, you want to make sure that that portion of your life, the financial portion of your life, takes care of the spouse and the children to help them lessen the blow of being without you. That's number one. The only other second thing that could possibly happen is you become sick, hurt, disabled, strodo. In my case, I had cancer, and I didn't work for over three
years. I was in a very, very bad way, and I have not had this plan. I would not bar from living under a freeway overpass with a cardboard box, because the amount of money that it cost me to be able to maintain my health and to maintain my lifestyle was significantly more than I'd ever would have gotten on unemployment or anything like that. These plans are phenomenal. Basically, what happens is you're allowed to access a portion of the death benefit for a living benefit to help you get to where you need to be, or to settle your estate, or to make sure that your family is being taken care of while you are not working. So those are called the living benefit programs. So again, number one, you may die. Number two, you may become sick, hurt, or disabled. The third option, you live. Yay. But if you live, and you get into retirement,
you're going to need money. Now that gets back to what are we doing now to make sure that third option is the way you want it to be when you choose to retire? And are we able to access it in the most tax advantage away possible? So in my opinion, there is no better place to push your money than a fixed indexed life insurance policy. Stocks, bonds, mutual funds, all that is not the ticket. Because all that does, even if it goes up, if it doubles in value, well, you've just created yourself a very large tax bill. People don't think about that. I try to show people how to get no tax, and especially when you get to be my age, I'm 67 years old, and you start taking social security. If you make too much, people don't understand that even it's not just you.
Let's say you have social security. The average amounts about $2,500 a month in the US. You take that income over $30,000 a year, and now you're married with someone, and they make $30,000 a year. That puts you over a threshold for the IRS to now come in and start taxing your social security up to 85% of it will be taxed at ordinary income rates up to 39%. So the money you thought you were getting for retirement now is this much because of the taxation of both of your incomes. So the benefit of being in the correct type of life insurance policy, you are able to access that money on a complete tax-free basis if you do it correctly.
So I hope that answered the question. Yes, it did answer the question, and it kind of made me have a different question on the other end of the spectrum. I'm wondering if there is such thing as free long-term care insurance. Yes, ma'am, that's what I was just talking about, those stop free, it's part of your policy. There's certain fees that go along with maintaining the life insurance policy. And so if you become sick, herder disabled, that's what that living benefit is about. And that is in turn an option to be able to have in a sense free long-term care. But you've got to qualify for the life insurance plan. That's why it's important for people to purchase a plan early as they can, as soon as they can, because it's based on two things. One is your health. Two is your age.
You're never as young as you are right now. Oops, you're already older. You're never as healthy as you are right now, unless something else has happened in your life or you have an unhealthy lifestyle. You can change that, and you can get in a better rating for yourself. But the age you can't do. So yes, in a way, it's like a free long-term care policy. If you can't qualify for the life plan, there are certain types of vehicles out there where you can deposit money. I did it for my mom, actually, and I talk about that in one of the chapters in the book. She was too old to qualify for a life insurance plan. She had money that was sitting in a CD that was earning like two, three percent, nothing, basically. And yet that two or three percent still, you get a $10.99 at the end of the year and pay tax on that little amount. So we were able to take her CD. She was healthy enough physically and cognitively
to answer a few questions with a nurse. And as she was able to answer those questions, they were able to triple that amount. So she had $100,000 that she had sitting in a CD that she'd had for years from when her husband died. Just sat there earning basically nothing. She had no long-term care insurance. So we took this money, I put it in this one particular plan and that tripled it to $300,000 of long-term care benefits should she need it. And that's exactly what happened. She did end up having dementia and she was in care for about nine, almost 10 months. And so paying for that care. Instead of us having to write a check for it or depleting her estate, attaching her home or selling other assets of hers, we were able to then leverage that money that formerly was in the CD,
put into this new type of plan. Instead of a $100,000 benefit, she had a $300,000 benefit. So there's lots of things that people can do if they ask the right questions to the right type of advisor, someone like myself. The very beginning of my book, even before I even get into the chapters, I pretty much rip on 95% of the brokers and advisors out there because they do the wrong things. They're all concerned about accumulation, accumulation, accumulation, assets under management for them. They don't really have the best interest of the person in play. And I say I'm there. I said, I'm happy to speak with you or any one of your advisors at any time and go over this. Happy to reach out to me. My address is at the back of the book. So I hope that answered that question for you.
Yes, it did. I want to switch gears just a little bit and ask you about what are your thoughts on annuities? Is it something we can be concerned about? That's a great question. I'm sorry about it. Is it a good thing or? That's one of the things I do mention in the book as well because people ask about them. Annuity is in a contract that's issued by an insurance company. There is, I mean, repeat this really carefully for people. There is no place safer in the world that you can put your money than with an insurance, a fixed insurance company. There is no place safer allowed by law than with a fixed life insurance company. Now, what do I mean by that? A fixed life insurance company like an annuity or a fixed life policy, a fixed annuity. The money goes into the account.
Automatically, from that moment, they're required by several different mechanisms. One of them is called the legal reserve system. Not the Federal Reserve, the Federal Reserve is a joke. The legal reserve system requires that insurance company. Let's call them the ABC company for right now. Requires the ABC company to not only back up your money with their money, with your money. So let's say you've got $50,000 you put into an annuity. The ABC company has to match that $50,000 and put it in a separate account and add 5% more to it to be available within 30 days on demand to you, the policy holder. So a fixed annuity, there is really nothing better out there. It's a matter of fact, you said you live in Atlanta or that's your hometown, the ATL. I was born and raised in Chicago
then I moved to Atlanta for a number of years and then I came back to Chicago for my family. Okay, a lot of states have something called a lottery system. I'm not sure if Chicago Illinois does, but you've heard of winning the lotto? Yes. Okay, if a person's smart, they don't take the cash amount. So if somebody wins 50 million, the lottery company doesn't write them a check for 50 million. They'll give you a cash amount for like 30. The smarter option is to take the 20 year payout to get the full 50 million. That doesn't happen as often as it should, but when it does happen, the insurance company is required by law to purchase a fixed commercial annuity to disperse the money to you, the winner. They can't do it.
The state is not allowed to do it because they don't want funds being co-mingled with their state budgets and other funds and other obligations. So they're required by law to fund an annuity. Again, there's no safer place allowed by law that you could put money, that a fixed insurance annuity or life product. The states do it. They're required by law to do it. If you win a settlement against somebody in a lawsuit and it's a structured payout, they're required by law to put that money into a fixed annuity to pay you your due over time to make sure it's there. Insurance companies do only one thing. They mitigate risk. They make sure that the risk that is potentially out there or financially out there does not affect you and your payment or your funds. So I'm a huge proponent of them. Yeah, do I think you should have a little money in stocks? Yeah, probably.
Only what you can afford to lose. But then again, you gotta look at, let's say it makes a bunch. That in turn creates a larger tax problem. So there's a lot of ways to structure things, but doing it at the beginning is the right and proper way to do something. And if a couple is married, like I said at the beginning of your show, a big proponent of making sure women are taken care of. And if they're married to a man, of course, in this case, you wanna make sure that man has a life insurance policy for you should that spouse become sick, hurt or disabled or die, get hit by a boss or a cement mixer. That pays out a policy amount to the surviving spouse. So anyway, that's my two cents worth on that. Okay, that's very informative. I think that was very informative. Thank you for that information. We all, yes, thank you.
We all can use that information. Also, I had another question, one of the switch gears, just a little bit when it comes to an R-R-A. So what's the difference between a regular I-R-A and a Roth I-R-A? Great question. You probably have heard in life that if something's too good to be true, either it is or they limit how much of it you can have, correct? Yes. Okay, the Roth I-R-A is such a good deal that the government limits how much you can contribute to it each year depending upon your age. If you're over the age of 50, you can put in up to $8,000 a year. If you're under that, you can only put in six.
Now, you can convert other assets into a Roth and pay the tax, which is a no-discussion we'll have either later in this show or another time. Or if you have an I-R-A, that's a regular I-R-A somewhere that you've had at Bob's Bank or whatever the case may be. That I-R-A is the worst thing you can have. And let me tell you why. You've mentioned earlier, Fierce, that you have a concern with the I-R-S, which means a tax liability. Yes. So I don't know your age, but I'll tell you mine, I'm 67. I'm 62. Okay, the whole time you and I have been alive, taxes have never been as low as they are right now. So in six years and 42 months, what's the tax rate going to be?
In nine years and 12 days, what's the tax rate going to be? Shoot for that matter, in five years and 84 days, what's the tax rate going to be? You don't know, neither do I. But the point is, there will be taxes. So the I-R-A that a person has now, they are better off converting that, this is that conversation I said we're gonna have, converting that to a Roth I-R-A now and paying the taxes due on it now. So let's say you have a $50,000 I-R-A, you can convert that to a Roth I-R-A and you would pay the income tax as ordinary income on that $50,000 in conjunction with whatever you earn each year. So hopefully if someone is still working,
they have write-offs, exclusions, deductions and they can loosen that tax obligation a little bit. But the benefit of converting to a Roth, you've now converted, let's just say you paid $8,000 in taxes on that, now you have 42,000 in a Roth, which means that thing can grow and you want it to grow, grow and grow and grow, let's say it quadruples in size. Now it's $160,000, yay! You can start taking that money out after age 59 and a half and not pay any tax. On the amount or the growth at all. So it's a wonderful thing to be able to convert an I-R-A or a 401K into a Roth product now. The problem, and I said at the beginning of my book and I said a little bit ago on our initial conversation,
most advisors out there do the wrong thing for people. And I'm going to bet you have heard what I'm going to share with you. The whole time I was growing up and earning money, there was always two things that were said. Number one, work hard, put your money into an I-R-A and put it into a 401K. Stuff that thing as full as you can. And then the other thing they say is defer, defer, defer. Have you heard those things before? Yes. Bad advice. All they're doing is delaying the unknown tax obligation that you will have in the future. People say, oh, well, I just won't use my I-R-A then. Any wrong answer? Because at age 72, you have to start taking it whether you want to or not. So, matter of fact, I would say probably close to about 65% of the people in that age group that I've worked with
wish they never had an I-R-A because they're forced to take distributions, which in turn causes their social security to be taxed. And if you don't take the exact amount of that RMD, you are taxed at 50% and still have to take it out and pay the tax. So, get out of the I-R-A's, get out of the 401K's, get into a Roth or get into a decent life product. In the back of my book, you can, anybody can reach me. I'm happy to work with anybody. I don't even charge. That's phenomenal. That's why I said, I've been a lifesaver for people and their lives and their retirement lives. I don't care if you're 20 years old. I don't care if you're 20 years old or 80 years old. I've worked with them all. I've learned a lot during this session. This has been very informative.
I told you, I'm the biggest best interview ever. Yeah, a lot of information. A lot of information, very informed. I wish you had a pen I wanted to take some notes. Well, you could just replay it. Yes, well, actually, you're correct. You're right. Because I'm still thinking about the fixed insurance for the annuities. I'm loving that. I love that. Shout out to me, offline. And, you know, hey, I got this. I want to do this. And I'll give you some ideas. And if you want to do it with me, I'm happy to do it for you. I'm licensed everywhere. I've been doing this 40 years. As you can tell, I know what I'm talking about. Absolutely, absolutely. Very interesting. We've got a lot of questions. Not for right now, we have a lot of questions. So listen, well, I'm not going to talk about that. I was thinking about talking about a trust that my husband had many years ago.
But we'll talk about that on the flip side. I don't want to talk about that right now over the air. So we'll talk about that a little bit later. But I do want you to, what's the one important thing, the most important thing we can do when it comes to our financial picture? What's the one thing that anyone can do at any age to help their financial health? I'll put it that way. Dirt now. Tomorrow's too late. Any amount is the right amount. There comes a time. Remember I said five years, now you're going to be what? Five years older. Five years ago, you were what? Five years younger. Even if you would have had, or anybody out there can create the discipline for themselves to put aside $100 a month.
I know it's tough for some people, but go without a couple of lattes a week. Go without whatever. And because five years now, you're going to be five years older. Would you rather be five years older with an extra $10,000, $15,000 in the bank? And then when you get to be retirement age, that money turns into more, of course you would. And you're going to want that latte or whatever it may be, just as much as not more when you get older, but you won't have the capacity to earn it as well. Unfortunately, that happens to people. We age out of the workplace, and then leaves people to do their own devices to try to look for different streams of income for themselves. So the most important thing you can do is start now. Some amount, any amount,
discipline yourself and not to touch it. Treat it like a bill. Treat it like, you know, a fierce future financial bill. Anybody just start something in something. Do something to put it out of immediate, disposable income. Take it out of the right front pocket and put it in some kind of account somewhere else. That's the most important thing. Then you start looking at the next most important thing is getting the right type of tax favorable products in which to allow it to grow. Like an annuity grows in what they call triple tax deferred. You earn interest on your interest. You earn interest on the overall amount. And you earn interest on the money you would have spent in taxes
because it's a completely tax deferred vehicle. Now if you can get a Roth fixed indexed annuity, then all of that money, all that growth is not subject to state or federal taxes. Now we're in the future when you start to take it out. Okay. That makes sense. You know, I was listening to what you were saying. And, you know, I can't help but to think about some really great people I've known during my lifetime. And one person that keeps popping up was Karen. Karen Penny, she was vice president. I'm sure she's retired by now in all these years. Karen Penny, I was her administrative assistant to a vice president at the bank, largest bank in Louisiana at that time, her burning bank, and she would always say to me, she was real smart lady, you know. She would always say to me, Adrian, start right now, start right now, you know,
save something, do it right now. You won't miss the money. She would always say, take out the money and put it in, you know, whatever account you choose to, like you said, whether it's R.A., whether it's a Roth, you know, just make a decision and start right now. And another person, when I was at DePaul University, it was just a department secretary to 22 finance professors. They would tell me the same thing, my bosses. Start right now, don't wait, don't wait. You're not gonna miss the money to start. Take out a little something, they would say the same thing just when you said, just start. Start, you won't miss the 10 or 15 dollars or 20 bucks, whatever you wanna put aside. You'll have something, you're nested, you know, growing. That's right. That's very good advice. That's right. So yeah, you left a very, very huge impression. You know, if we all make the mistake, I'm not gonna lie. I've made that mistake because even the days when I was at DePaul, I don't know what,
I was younger, I was so much younger, and it didn't, it was important, but I didn't see it as like I need to do it right then. And they'd say, Adrian, start right now, you know, take the money out and put it in, you know, yes, savings account, the R.A., you know, whichever account you wanna do it in. Now it's like, okay, I'm 62, I need to have done, you know, a lot of things different. So yeah, huge impression. Huge impression and so on. Oh my goodness. What about, the next thing, the next best thing, and I don't mean to sound like I'm a broken record. I was telling you before, I think everyone, whether it's get the e-book or actually purchase the soft copy, this will change your life as far as the way you look at your financial future. And it will change the way that your financial future
will treat you if you just read this book and grab it by the hand and start applying these things in your life. And I'll share with you, a majority of the chapters in there are actually clients of mine that I share the stories, like you were sharing those stories of the people that were trying to get you to do something. Well, I'm sharing the stories of what people that I worked with on there. To, I told you, I did 762 live speaking engagements in 35 different states. And inevitably, within 90 days, someone would always reach out to me and they go, hey, I met you at Indianapolis. Oh, I met you in Atlanta. Oh, I met you in LA or I met you wherever I was. And you spoke so well about these things that we should be looking at and doing.
And I don't know if you remember my husband, Bob, well, Bob died about a month and a half ago. And I don't know what to do. Or my wife just got sick and we need to start doing something. Problem is, you know, I'm just an old Iowa farm boy. You heard about people are trying to close the gate after the cattle are already out. You need to close the gate before they get out. Yes. And too many people are sitting there thinking it's an insurmountable task, but just do it. You've got to start putting something away now. Close the gate, do something for yourself because no one has a crystal ball. But I've made a career and a lot of friends by looking at all the what ifs can happen because you've heard the the old line everyone has truth is stranger than fiction.
And I have seen so much truth, and I have to write a whole book just about those. But it's something that needs to be taken to heart and everything that you and I have spoke of today. Obviously it's resonating with you, but it's in the book and these are things that are not taught by other financial advisors, not taught in schools and not taught in the lessons of life. You need to have somebody that's specialized in the things that I've specialized in for 40 years. And this book does that, even if you get the ebook for six bucks on one of the places, or the most people get the paper back because they want to go back, they use those to work, book, they highlight things and then they go back and look at it and then the write notes and then they'll email me or whatever. But do whatever person needs to do but get the knowledge.
Wow, that's a mouthful. I'm just kind of marinating on that a little bit because you said that the things in your book are just things that is not taught about in schools, not taught about. Not a thing. Ooh. None of that is. Mm. Because I know what they teach us and so I'm very curious because I know what I've been taught over my lifetime during the times when I was working. I never thought that I would get to a point where I had a serious major health challenge. You know what I mean? And I had to go without a paycheck. I didn't have any kind of check coming in. I was young. I was in my 30s and it changed my life tremendously. So yes, oh my goodness. I was 33. I have been a professional athlete many years before in a different industry.
I never smoked. I drank a beer once in a while. And I ended up, all of a sudden, having incredible pains in my chest and heartburn, nonstop. And I ended up having a soft, jeal cancer. Never smoked, never drank, never any of those kind of problems. But I spent three years in the hospital with different surgeries and three open chest surgeries to save my life and put me back together. Now, if a person right now looks at their own life and imagine not getting a paycheck for over three years, what kind of shape are they going to be? That's why I'm a big proponent of making sure you have the right types of insurance in your life that are going to take care of you financially. And they're going to make sure that you're going to be OK. If I didn't have that, I don't know where I would have been.
Well, hmm, oh my goodness. Ooh, that just speaks of volumes. Yep, I mean, here I was. I was, you know, a top athlete, great shape, phenomenal shape. And all of a sudden, bam, I'm knocked out of the game. Not goodness. And I didn't do anything. It's not like I was reckless or careless. Turns out that I had a genetic defect in my pyloric valve, which is the thing that stops the acid from coming up to your esophagus. And I had a pyloric cancer. And I was 33 years old. By the time I got done, I was 36 going on 37. Not goodness. But no one has a crystal ball. Same thing you said. You were a younger woman. And anybody listening to this recording or watching it needs to really, how many times
are you driving out somewhere? The sun fool almost hits you and blow you up. But you know, oh my goodness, just so many stories. My brother, my younger brother, he got hit. This was many years, he was young. Many years ago, he got hit by a drunk driver. And I was, unfortunately, in Louisiana at the time, my mother called. She says, your brother's in hospital and messed him up. So he's OK now. He's fine now. But for a long time, he lived with pain and different things that was going on. And it's probably because of a drunk driver that hit him. He was coming out from work and trying to get home. So wow, you know, I want to wrap up this. I hope you enjoyed your time with me, I did. I did. So I got to get moving like right now today, you know. And I also run, like I said, to your earlier call center and they don't take out taxes.
And you know, you got a lot of us, 1099s, that got to get in the habit of making sure our taxes are taken care of. And you can slide through, you want to say, I'll put it this way. I'll put it this way. I won't use anybody's story. During COVID, a lot of people was making a lot of money in my industry, what we do during COVID. We was on the flip side. You either weren't making money or you wanted people serving, helping people to get the money. A lot of people were making money. And I don't know if they were taken out the cash to pay their taxes. So a lot of people, a lot of us, got in trouble. In our hours of sand, you remember you still all me? You know, and so that's not a good thing. That's a terrible thing. No, no. But the old line, there's two things to be sure of, death and taxes. And one of them, you can't do anything about the other one you can. Yeah.
So I can't wait to talk through some more. But I do want to ask you for those who are listening in. And I do want to thank all the international listeners just listening to the program in Portugal, Malaysia, India, West Africa, the UK. I do appreciate you guys for always listening. And I thank you. Thank you so much for listening and Poland. Do have a small listenership in Poland. So I do want to ask you for those interesting how they can contact you. They want to reach out to you. What should they do to contact you? What's the best way? Yeah, they can, you know, if, and I don't care if you're in a different country, as you know, you and I have been able to connect because I've been in France. I have a house there, and we were there for the holidays. And I have, French people ask me about what they should be doing, you know, the taxes are completely different in Europe. But the principle of needing money doesn't matter.
What country are you in? So I'm having what age you are. Everyone's going to need it. So I always, very strongly recommend that everybody, you know, at least understands the options that are available for them out there. My email address directly to me, I don't know if you can see it on here or not, but it's tax free zero at gmail.com. Oh, I see. It's in the back of my book. If you get the book, you'll have all the knowledge I've shared today. You'll have my personal information. You'll have my email to get a hold of me. You'll have every single single thing there. But tax free zero at gmail.com. Tax free zero at gmail.com will get people routed to me. And I'm more than happy to speak to people. I mean, I get a lot of people,
so it's, give me a day or two. I have to get back to you. Okay. But I'm happy. Like I said, I could sell from this show, let's say a thousand copies. That'll be wonderful. But it's not going to make a difference financially in my life. It's wonderful. It covers the cost of all the money that I've spent doing it. But to me, the most important thing is getting the information out to you, to the people out there sitting there. The people that have been thinking about it, the people that have been on the sidelines, the people that haven't put 10, 20 bucks a week away or haven't understood the why and because of needing to do that. This is something you can't wait. Because you're going to be five years older from now, five years from now, 10 years older, 10 years from now.
And if you die, then the money you put aside goes to people you care about. But if you live, yay, you've got money. You've got a few bucks at a side. You can't count on, and I talk in here in depth and a couple of chapters. Social security is due to run out of money pretty soon. They're going to have to have some emergency stopgap sessions within the next two congress cycles. Medicare is due to run out of money also. Let me leave you with one other thing that I put in my book. Let me tell you, share with you why taxes are going to go up. You ready? Yes. For every dollar, the government takes in. 95 cents of that dollar goes to only three areas.
Medicare, Medicaid, social security, and just the interest on the debt, not even touching the principle of the debt, just the interest, social security, and Medicare, Medicaid. That's it. So that means the entire US government, the Army, the Air Force, the Marines, the Navy, the Coast Guard, the Forest Service, FBI, IRS, ICE, Department of Transportation, any branch of the government you can name. And everybody that's retired from there and getting a retirement check is paid with five cents of each dollar.
Could you run your house on five cents? There's no. So where are they going to get the money? You, or your children, or your grandchildren, and your neighbor, and your other neighbor, and the people over there. So that's why this book is so darn important. Get to the zero tax bracket. Learned how to do it. So I hope that was informative, and I hope that sticks with people, and I hope it's a good enough call to action for people. I know that it was. I know this was, and I know that it's going to stick, and I do want to thank you for taking the time out of your schedule and come here today and share all this valuable information with the listening audience.
You're welcome. Thanks for having me. You're more than welcome. So guys, listen, I'm going to be back on tomorrow. I want you guys to make sure you subscribe on Spotify, Apple, whichever platform you're, like, listen to, make sure you click that subscribe, but not really, really, really do appreciate it. So listen, guys, I got to get on up out of here. It's been a stone coal blast. And as always, it's peace, love, and sooo. You motivated. You motivated. You win and win. You know that. You
More episodes
More from The Fierce Female Network

Featuring "Complicated" by Cammellio: Before You Fall in Love, Ask This...
The Fierce Female Network

Featuring Friends by Sadie Miller Ep 2473
The Fierce Female Network
When Fear Takes Over, Say “Let There Be Light”
The Fierce Female Network
Work And Live In The Word Episode #2471
The Fierce Female Network